Rising Rate-Hike Expectations and AI Stock Volatility Drive Markets
Market Highlights
As of 16 November 2026, Fidelity International noted that markets have navigated the crisis at NVIDIA and growing scepticism about AI with surprising resilience, which looks more like a rotation than a correction, but attention is shifting to rising bond yields and a higher cost of capital; Schroders sees inflation as the key concern and expects further Fed tightening. Invesco believes AI demand and earnings fundamentals remain solid. Allianz Global Investors noted that easing US–Iran tensions pushed oil prices lower, while a strong US dollar weighed on gold; the US Dollar Index climbed to its highest level since April 2025.
Sources: Fidelity International, Invesco, Schroders, Allianz Global Investors (as of 16 November 2026).
Market Dynamics
Theme 1: Inflation Beats Expectations; Expectations for a December Fed Hike Rise.
Fidelity International sees a more stagflationary environment, with growth moderating from elevated levels while persistent inflation and higher bond yields create more uncertainty for risk assets; it views US growth as resilient but flags further Fed tightening and fiscal concerns, adding that market attention is shifting to rising bond yields and a higher cost of capital – typically what ends bull markets. Schroders said solid US growth and a tightening labour market risk exacerbating an already alarming inflation outlook, and that the Fed will likely have to go beyond reversing the "insurance" cuts of 2025 to rein in price pressures; it also expects one final ECB rate hike in December and sees the Bank of England in a modest tightening cycle.
Sources: Fidelity International, Global Asset Allocation Insights – November 2026 (November 2026); Fidelity International, Bulls, bears and bond yields (16 November 2026); Schroders, Economic and Strategy Viewpoint – Q4 2026 (8 November 2026).
Theme 2: AI Tech Stocks Turn More Volatile as NVIDIA Leadership Change Takes Centre Stage
Fidelity International noted that markets have navigated the crisis at NVIDIA and growing scepticism about the AI story with surprising resilience, looking more like a rotation than a correction. Its equity team sees AI demand persisting, but physical bottlenecks such as power supply and data-centre construction could stretch the investment cycle; earnings remain an important anchor, with S&P 500 third-quarter earnings growth of around 30% and most companies beating estimates. Invesco believes AI sceptics may be overlooking strong demand, solid earnings and fundamentals that may continue to support the stock market.
Sources: Fidelity International, Bulls, bears and bond yields (16 November 2026); Fidelity International, Equities Monthly November 2026 (November 2026); Invesco, Why the AI story may be stronger than skeptics think (16 November 2026).
Theme 3: US–Iran Developments Drive Oil Prices; Strong Dollar Weighs on Gold
Allianz Global Investors noted that supply risks around the Strait of Hormuz drove Brent crude sharply higher in October, but oil has since retreated on hopes of de-escalation with Iran. It remains constructive on commodities, as supply disruption benefits oil and constrained supply supports copper, but is more cautious on gold given high real yields and a strong US dollar, which it favours. Fidelity International cautions that further escalation with Iran or disruption to energy supplies could renew inflation pressures and raise the risk of a more prolonged stagflationary environment.
Sources: Allianz Global Investors, Multi Asset Tactical View: November 2026 (13 November 2026); Fidelity International, Global Asset Allocation Insights – November 2026 (November 2026).
Theme 4: Long-Term AI View Unchanged; Higher Yields Make Bonds More Attractive
BlackRock Investment Institute said recent tech-stock volatility reflects growing uncertainty over the scale of AI infrastructure investment and its earnings outlook. It holds a neutral tactical view on US equities over a 6- to 12-month horizon, but remains confident that AI will lift productivity and corporate earnings over the long term, maintaining a strategic overweight in US equities and favouring US healthcare, technology and financial companies. Meanwhile, the significant rise in yields has made bonds more attractive: for the first time since 2020, the institute has turned positive on interest-rate risk, with a particular preference for inflation-linked bonds.
Source: BlackRock Investment Institute, Weekly Market Commentary, 16 November 2026.
Market Performance
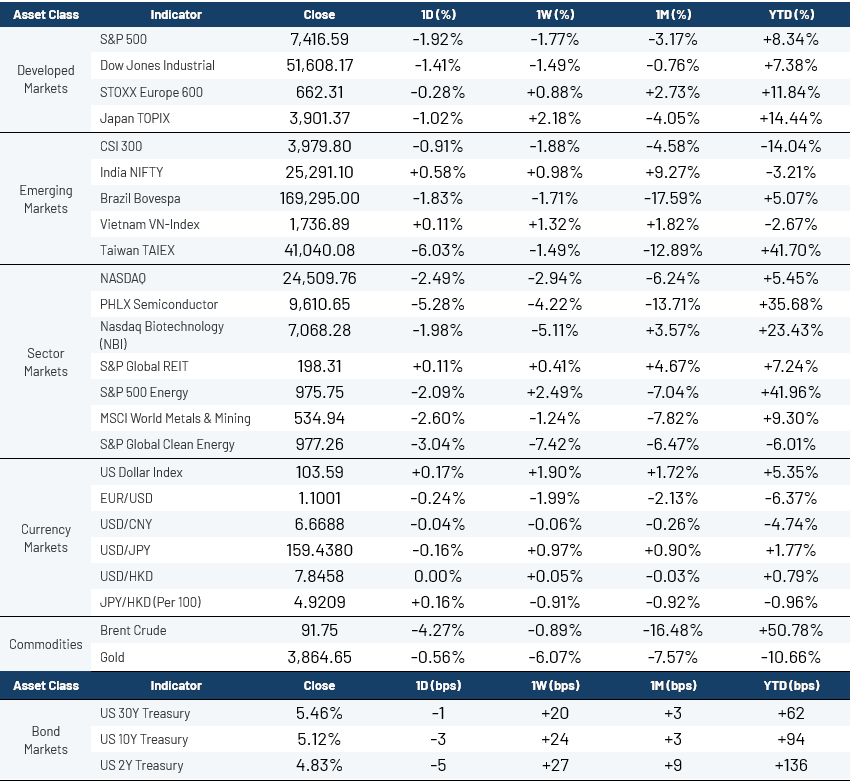
Market Data Date
2026-11-16 (based on each market’s previous trading-day close; 1W compared with the 2026-11-09 close, 1M compared with the 2026-10-16 close)
Data Notes
Equity / index / commodity / FX returns: latest close ÷ comparison-date close − 1; YTD compared with the last trading day of 2025.
Bond changes: latest yield − comparison-date yield (bps); YTD compared with 2025/12/31.
Main sources: MSCI, Investing.com, Yahoo Finance, The Wall Street Journal, StockQ, MSN Money, MarketScreener, MacroMicro, U.S. Department of the Treasury.
S&P Global Clean Energy and S&P Global REIT (S&P Global REIT, USD) use 2026-11-16 closing data (Clean Energy 1M is calculated using the 2026-10-16 close published by Investing.com). MSCI World Metals & Mining (price index) uses 2026-11-12 closing data.YTD figures for India NIFTY, S&P 500 Energy, S&P Global Clean Energy, Brent crude, gold, the currency pairs and US Treasuries are derived from the end-2025 closing baselines in the previous report.
Data Sources
Market Highlights and Market Dynamics
• Fidelity International – Bulls, bears and bond yields (16 November 2026)
• Fidelity International – Global Asset Allocation Insights – November 2026
• Fidelity International – Equities Monthly November 2026
• Invesco – Why the AI story may be stronger than skeptics think (16 November 2026)
• Schroders – Economic and Strategy Viewpoint – Q4 2026 (8 November 2026)
• Allianz Global Investors – Multi Asset Tactical View: November 2026 (13 November 2026)
• BlackRock Investment Institute – Weekly Market Commentary (16 November 2026)
• Portfolio Terminal – US Dollar Index (DXY)
Disclaimer
This document is for general information only. The information or opinions herein shall not be construed as professional financial, legal or investment advice or any offer, solicitation, recommendation, comment or any guarantee to the purchase or sale of any investment products or services. This document is for general evaluation only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person or class of persons and it has not been prepared for any particular person or class of persons. The investment products or services mentioned in this document are not equivalent to, nor should it be treated as a substitute for, time deposit, and are not protected by the Deposit Protection Scheme in Hong Kong.
The information or opinions presented have been developed internally and/or taken from sources believed to be reliable by WeLab Bank, and have been organised and compiled with the assistance of artificial intelligence tools. WeLab Bank makes no warranties or representation as to the accuracy, correctness, reliabilities or otherwise with respect to such information or opinion, and assume no responsibility for any omissions or errors in the content of this document. WeLab Bank does not take responsibility for nor does WeLab Bank endorse such information or opinion. You should exercise independent judgment or consult a qualified professional before acting on any information provided here.
Investment involves risks. The price of an investment product may go up as well as down and the investment product may become valueless. Past performance is not indicative of future results. WeLab Bank makes no representation or warranty regarding future performance. Any forecast contained herein as to likely future movements in interest rates, foreign exchange rates or markets or likely future events or occurrences constitutes an opinion only and is not indicative of actual future movements in interest rates, foreign exchange rates or market prices or actual future events or occurrences (as the case may be).
You should not make any investment decision purely based on this document. Before making any investment decisions, you should consider your own financial situation, investment objectives and experiences, risk acceptance and ability to understand the nature and risks of the relevant product(s). WeLab Bank accepts no liability for any direct, special, indirect, consequential, incidental damages or other loss or damage of any kind arising from any use of or reliance on the information or opinion herein. You should seek advice from independent financial adviser if needed.
Welab Bank Limited (“WeLab Bank”) is an authorised institution under Part IV of the Banking Ordinance and a registered institution under the Securities and Futures Ordinance (CE Number: BOJ558) to conduct Type 1 (dealing in securities) and Type 4 (advising on securities) regulated activities.
This document is issued by WeLab Bank. The contents of this document have not been reviewed by the Securities and Futures Commission in Hong Kong