Must-Read Before Applying for Tax Loans | 3 Tips for Choosing the Best Tax Loan & Improving Your Credit Rating!
For Hong Kong residents paying Salaries Tax or Provisional Tax, payments are usually split into two instalments: the first in January and the second in April. That’s why October to April is peak season for tax loan (also known as tax season personal instalment loan). Banks and financial institutions often promote these loans with low interest rates, cash or points rebates, fast approval, and flexible repayment terms.
But when everyone claims “lowest rate in the market” or even “0% interest,” how do you choose wisely and ensure you’re really getting a low-interest tax loan? Here are 3 key tips to help you decode the secrets behind low-interest tax loans!
Tip 1 | A Good Credit Rating = Easier Approval & Lower Interest Rates
When you apply for a tax loan, lenders typically check your credit report from Credit Reference Agencies like TransUnion to assess your risk and repayment ability. Your credit report is crucial—it includes your repayment history, total outstanding debt, and overall credit records, all of which affect your credit rating.
If you’ve used credit cards or personal loans before, you already have a credit report that tracks your credit-related activities. Generally, the higher your credit rating, the more stable your credit profile, which means lenders see you as more likely to repay on time. This increases your chances of approval and getting a lower tax loan interest rate.
If your credit score is low, you may face:
· Higher loan interest rates
· Lower approved loan amounts
· Possible rejection
So, if you want a truly low-interest tax loan this season, maintaining a good credit record is essential!
3 Practical Ways to Improve Your Credit Rating
1️⃣ Don’t Rely Only on Cash | Build a Stable Credit History
Many people think “not borrowing = good credit,” but having no credit history makes it hard for lenders to assess your repayment ability. You can:
· Apply for one or two credit cards and use them responsibly
· Pay off balances on time every month to build a positive repayment record
· Longer and more stable credit history helps improve your score
2️⃣ Smart Credit Card Usage | Avoid Over-Reliance & Min Pay Trap
Credit utilization ratio matters—this includes your card balances and number of cards. If you only have one card and max it out, your score may drop. You can:
· Pay off your full balance monthly, not just the minimum payment
· Avoid applying for too many cards in a short time
· Consider increasing your credit limit (higher limit + lower balance ratio = better score)
3️⃣ Check Your Credit Report Regularly | Plan Ahead for Loan Applications
Credit report data usually comes from banks or financial institutions. If there’s an error, you can request corrections from agencies like TransUnion. If you plan to apply for a loan, check your score 6–12 months in advance to allow time for improvement. You can:
· Review your credit report regularly to maintain a healthy score
· Correct any errors promptly
✨Check your TransUnion credit report for FREE in just 4 steps via the WeLab Bank App!
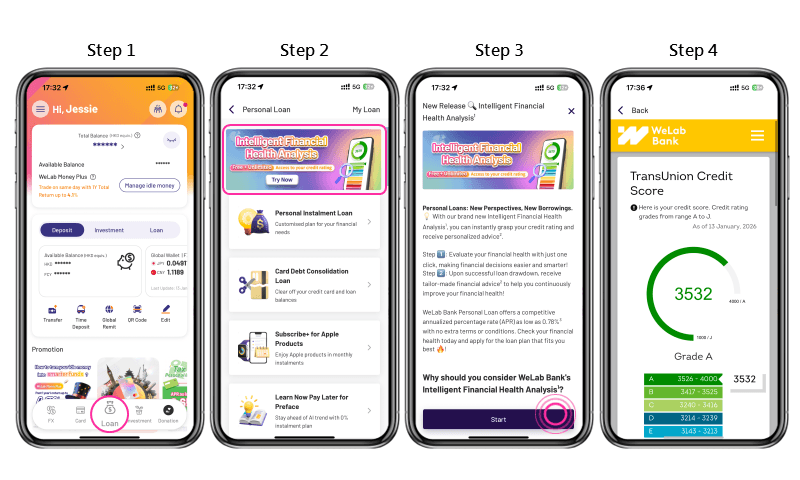
The screen displays and images on this website are for illustrative purpose only. Please refer to the information displayed in the WeLab Bank App on the transaction day.
Tip 2 | Stable Repayment Ability = Better Approval & Rates
Besides credit rating, your repayment ability is another key factor for tax loan approval and interest rates.
If you have a stable income, regular monthly salary, and can provide proof of income—especially if you work in government, professional roles, or other stable jobs—you’re more likely to get approved at lower rates.
Lenders also assess your overall financial health, including:
· Existing loans (e.g., mortgage, personal loans, credit card balances, etc.)
· Monthly fixed expenses (e.g., rent, utilities, food, transportation, insurance, etc.)
· Overall debt ratio
If your repayment ability is insufficient and your application is rejected, you can:
· Apply for a smaller loan amount
· Choose a longer repayment term to reduce monthly payments
(Note: Longer terms mean higher total interest, so consider your long-term affordability—not just monthly payments.)
Tip 3 | Choose Smartly: Understand Hidden Conditions Behind Tax Loan Offers
Every tax season, banks and lenders roll out attractive tax loan promotions—0% interest, low rates, cash rebates, reward points, fast approval, etc. But these offers often come with hidden conditions, such as:
· New customers only
· Minimum loan amount required
· Specific repayment terms
· Application via designated channels
· Deposit new funds into the bank
· Restricted to certain professions
👉 Read more: Tax Season Loan Survival Guide
With so many options, it’s worth spending time comparing offers. Before applying, check if you meet the conditions for the real “low interest” deal. Beyond maintaining a good credit rating, understanding the details during tax season and choosing a plan that fits your needs, financial situation, and repayment ability is the smartest move!
WeLab Bank Tax Season Loan Highlights 💰
WeLab Bank’s personal loan offers an APR as low as 1.28%1, plus cash rebate of up to HKD 23,8882 💰.
- HKD 0 handling fee
- Flexible repayment period of up to 60 months
- Greater flexibility in fund usage to meet different financial needs
- Loan amount up to HKD 1,500,000 or up to 18x monthly salary (whichever is lower)
👉 Learn more: Tax Season Loan Offers
To borrow or not to borrow? Borrow only if you can repay!
Remarks
1 Assuming a loan amount of HKD 500,001 with tenor of 24 months, the APR will be 1.28% (including a cash rebate of HKD 9,450) or 3.12% (without any cash rebate), and the total repayment amount will be HKD 516,181. The APR is calculated according to the guidelines issued in respect of the Code of Banking Practice and rounded to the nearest 2 decimal places. The APR is a reference rate, which includes all applicable interest rates, fees and charges of the product, expressed as an annualized rate. The final APR offered is subject to the applicant’s application information, personal credit record, and the final approval process.
2 From now on until 30 November 2026, successful WeLab Bank Personal Loan applicants with an approved loan of minimum of HKD 150,001 amount and tenor of 24 months or above can enjoy up to HKD 23,888 (for Personal Instalment Loan applicants) and HKD 23,888 (for Debt Consolidation Loan applicants) cash rebate if the loan is drawn down within 7 days after approval. The cash rebate amount will be credited into the HKD Core Account on or before 31 March 2027. Please refer to terms and conditions for more details.
Disclaimer
The information provided on the website is for general information only without warranty of any kind and may be changed at any time without prior notice.